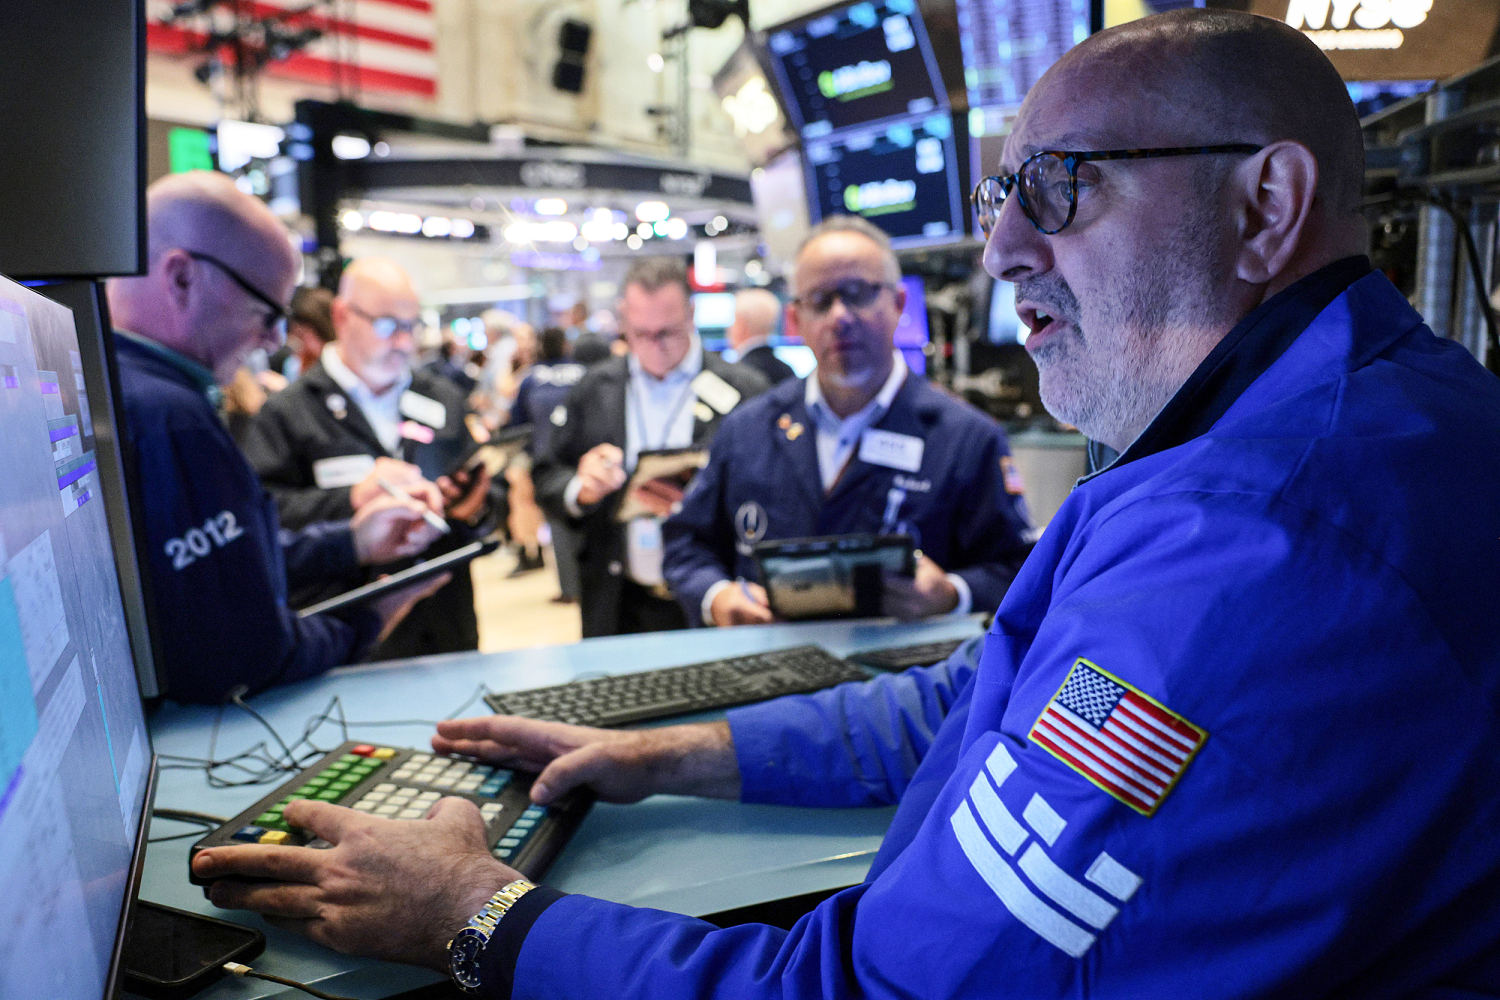
When Brent crude breaches the ninety-day moving average and pushes toward one hundred and ten dollars a barrel while technology indices shed a trillion dollars of market capitalization in a single trading session, the market is not experiencing random volatility. It is executing a rapid, involuntary repricing of duration and cash flows. The simultaneous compression of high-multiple equity valuations and the expansion of commodity input costs reveal a structural transmission mechanism that connects geopolitical energy supply constraints directly to the discount rates applied to future technology earnings.
Understanding this dynamic requires abandoning surface-level market commentary about sentiment and focusing instead on three fundamental pillars: the capital expenditure cycle of hyper-growth firms, the cost-of-capital function governed by sovereign bond yields, and the energy intensity of digital infrastructure.
The Duration Trap in High-Multiple Equities
Equity valuation is fundamentally an exercise in present value calculations. For mature, cash-generative businesses, the majority of cash flows materialize in the near term, rendering them relatively resilient to shifts in discount rates. Conversely, technology firms—particularly software, semiconductor design, and pre-revenue platform businesses—exhibit long-duration cash flow profiles. Their projected earnings are heavily weighted toward the outer years of financial models.
When energy prices spike violently, the immediate secondary effect is an inflationary impulse that forces central banks to maintain restrictive monetary policy. This dynamic alters the denominator in present-value equations. As the risk-free rate rises to combat energy-driven inflation, the present value of earnings expected five or ten years into the future contracts disproportionately compared to near-term cash flows.
[Energy Supply Constraint]
       ↓
[Input Cost Inflation]
       ↓
[Persistent Monetary Tightening]
       ↓
[Expansion of Discount Rate (r)]
       ↓
[Disproportionate Compression of Long-Duration Equity Valuations]
This structural reality explains why a spike in oil prices acts as a direct tax on long-duration assets. The market is simultaneously recalculating the cost of capital and discounting future growth rates. Software multiples that traded at thirty times forward sales during periods of low interest rates and stable energy inputs become mathematically untenable when the cost of capital reflects a higher-risk macroeconomic baseline.
The Energy Cost Function of Digital Infrastructure
A common misconception among retail market participants is that software and internet enterprises are insulated from commodity price shocks because their primary asset is intellectual property. This view ignores the physical reality of the infrastructure required to run modern digital economies.
Data centers, artificial intelligence training clusters, semiconductor fabrication plants, and global logistics networks underpinning e-commerce are massive consumers of electricity. While a technology firm does not buy barrels of crude oil directly for its software engineers, the marginal cost of electricity is inextricably linked to the fossil fuel complex. Natural gas and coal frequently set the marginal clearing price for power grids, and oil prices often move in sympathy, driving up baseline operational expenditures across the technology sector.
When energy costs escalate sharply, the operating margins of hyperscalers and hardware manufacturers face an immediate squeeze. Unlike consumer-facing businesses with high pricing power and low fixed assets, capital-intensive technology infrastructure providers cannot instantly pass these cost increases onto enterprise customers locked into multi-year cloud service agreements.
Furthermore, the expansion of high-compute workloads—such as large language model training and inference—demands a secularly increasing volume of power. When power generation costs surge due to oil and broader energy market shocks, the capital expenditure required to scale computing capacity incurs an immediate efficiency penalty. Return on invested capital declines, forcing financial analysts to downgrade terminal growth rate assumptions.
The Macroeconomic Transmission Vector
The mechanics of a trillion-dollar market capitalization drawdown during an oil shock operate through a specific transmission sequence:
- Supply-Side Shock: Geopolitical friction or production quotas restrict petroleum supply, driving Brent crude to multi-month highs.
- Input and Transport Inflation: Higher energy costs ripple through manufacturing, logistics, and power generation, elevating input costs across the broader economy.
- Expectation Realignment: Bond markets reprice inflation risk, pushing sovereign yields upward and signaling that interest rate cuts will be delayed or reversed.
- Liquidity Contraction: Higher yields attract capital out of risk assets and into fixed income, altering the risk-adjusted return threshold for institutional allocators.
- Valuation De-rating: Quantitative models apply higher discount rates to long-duration tech earnings, triggering automated stop-losses and margin liquidations among leveraged growth portfolios.
This sequence highlights the fallacy of viewing asset classes in isolation. Technology stocks do not trade on code quality and addressable markets alone; they trade within a closed-loop macroeconomic system where energy acts as the primary thermodynamic constraint on economic growth.
Capital Allocation Under Structural Constraints
For practitioners managing balance sheets through macroeconomic regime shifts, the playbook shifts from multiple expansion to operational resilience. Firms holding substantial cash reserves and short cash conversion cycles can weather margin compression and capture market share from weaker competitors forced into dilutive financing rounds. Conversely, businesses dependent on continuous external capital injections to fund operating losses face severe solvency risks as financing windows close in response to rising energy-driven yields.
The strategic response to oil-driven market sell-offs is not tactical market timing, but the rigorous stress-testing of operational models against higher baseline energy and capital costs. Strategic advantage accrues to firms that possess genuine pricing power, energy-efficient infrastructure designs, and balance sheets unburdened by near-term debt refinancing obligations.